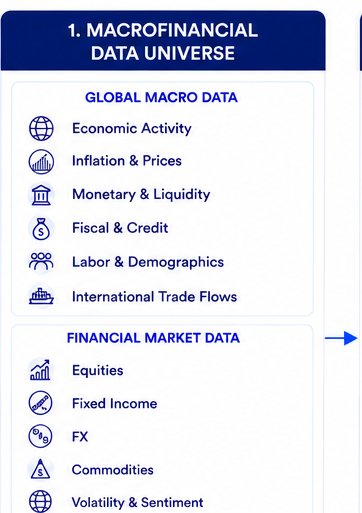
DeepBlue® is a systematic, machine-learning macro forecasting engine developed by MacroQuant, designed to spot macroeconomic regime shifts early and remove behavioural bias. Through merging deep institutional research with advanced data analytics (i.e. AI & Big Data), our global macro insights are robust and unique. We empower institutions with actionable & dynamic strategies, and risk-aware allocations.
![image of meeting with financial advisors [scene 3]](https://cdn.prod.website-files.com/6a5cbfd51e0faf9851054fd8/6a64c02733164a9b6aa559cf_DeepBlue.png)
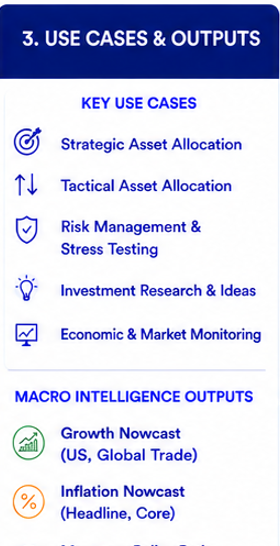
Using DeepBlue®, we deliver an "all weather" dynamic asset allocation strategy and insights for institutions.
Stay ahead of the curve through early identification of macroeconomic regime shifts, allowing for portfolio repositioning before consensus.
Adaptive models that protect your investments against big shifts in the world economy by building strong portfolios, thus having higher risk-adjusted returns and lower drawdowns.
Institutional-quality decision support, supports complex mandates with scalable, systematic solutions.
![[interface] interface of ai tool (for an ai saas company)](https://cdn.prod.website-files.com/6a5cbfd51e0faf9851054fd8/6a64d07ab8e8eadfba35219a_Chess.png)
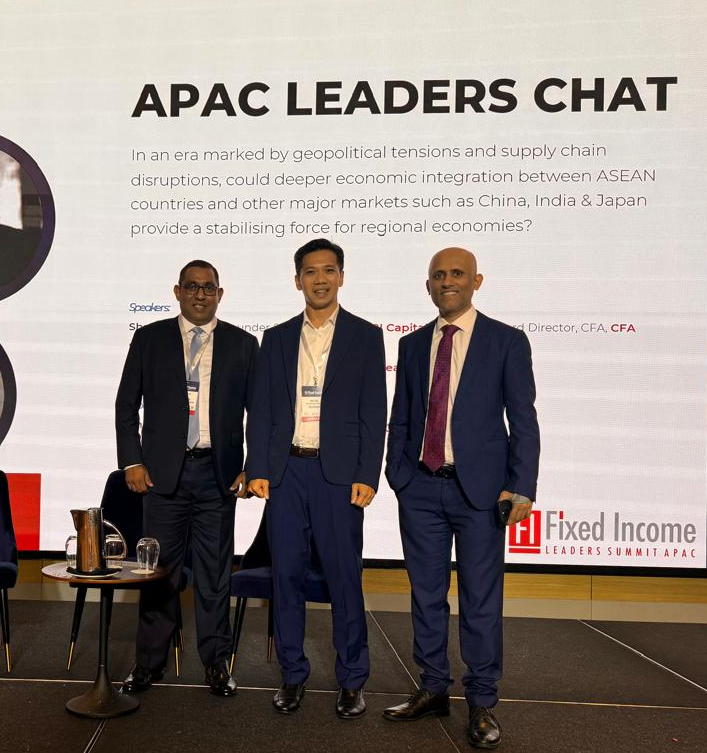
"It was great having you at the summit and was wonderful meeting you in-person as well! Really appreciate your time and effort in delivering great session and content to our audience."
![[headshot]](https://cdn.prod.website-files.com/6a5cbfd51e0faf9851054fd8/6a6586f4f395f8f206675e89_Yaro.png)

Systematic macro analysis for institutional decision-makers
![[background image] image of an open laptop in an office (for a ai healthcare company)](https://cdn.prod.website-files.com/6a5cbfd51e0faf9851054fd8/6a6eff3f6ecb7a47b52b16e4_MQ%20data%20dashboard.png)
AI-powered macro regime forecasting.
Remove bias with systematic analytics.
Dynamic allocation for institutions.
Your questions, expertly addressed
DeepBlue® serves as an independent, systematic tool that complements existing investment processes by evaluating the macro-financial cycle and calculating economic regime probabilities. It supports investment teams in identifying market turning points, reducing behavioral biases, and informing asset allocation decisions while leaving final choices with the institution.
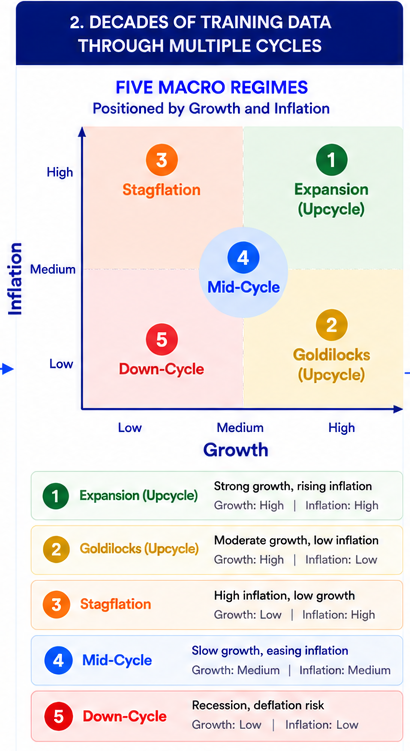
Traditional forecasting relies on fixed single-point estimates based on linear relationships, while DeepBlue® utilizes machine learning to identify non-linear connections and assign probabilities to alternative economic scenarios. This approach shifts focus from predicting a single outcome to evaluating multiple macroeconomic regimes.
DeepBlue® uses advanced machine learning like XGBoost and CatBoost to study macroeconomic and financial data.
DeepBlue® utilizes economic regime probabilities rather than binary forecasts to guide dynamic asset allocation across various asset classes, enabling flexible portfolio tilting based on risk conviction. This framework systematically adapts portfolio risk to changing macro environments while adhering to institutional constraints and benchmarks.
Institutions can evaluate DeepBlue® in stages, starting with historical validation across market cycles followed by shadow testing alongside existing processes to measure practical outcomes. Evaluation should focus on improved decision-making, risk-adjusted returns, reduced drawdowns, and how effectively the model fits within current risk and governance frameworks.
Request expert macro insights.